


Futures on the Nasdaq 100 (US100) and S&P 500 (US500) are down around 0.5% as Brent oil futures rise almost 1.5% above $105.70 per barrel following reports from The Wall Street Journal of a US strike on Iran's Qeshm Island. Shares of Apple and Palantir fell by approximately 2–3% following yesterday's quarterly earnings releases, despite both companies beating analysts' expectations.
Markets will closely monitor the results of the US midterm congressional elections, with the first results expected overnight, starting with Indiana and Kentucky. On the macroeconomic front, today's main events include the US JOLTS job openings report and factory orders data. Pfizer is scheduled to report earnings before the US market opens, while AMD and Arista Networks, two important companies within the artificial intelligence investment theme, will release their results after the closing bell.
Yesterday's Wall Street session was also marked by continued selling pressure on technology stocks, particularly semiconductor manufacturers, despite a sharp decline in oil prices. Although the largest technology companies struggled, most S&P 500 constituents finished the session higher, suggesting that selling pressure was concentrated primarily among the index's largest stocks, while the broader market showed greater resilience.
The Nasdaq 100 extended its losses yesterday and re-entered correction territory, falling 10% from its October peak. Meanwhile, a key semiconductor index lost a cumulative 12% over three sessions, highlighting persistent selling pressure in a sector that had previously been one of the main drivers of the US equity bull market.
According to comments made this morning by a senior Iranian official, mediators are still working to narrow the differences between Tehran and Washington. Iran continues to reject what it considers excessive US demands and insists that its conditions must be met before the Strait of Hormuz can reopen, with nuclear negotiations potentially beginning afterwards. Tehran has also warned that it is prepared to respond forcefully to American military strikes, both within the region and beyond.
The Reserve Bank of Australia (RBA) raised interest rates for the fifth time in 2026, from 4.60% to 4.85%, the highest level since 2008. The decision was in line with market expectations but was not unanimous, with six board members voting for a rate increase and three supporting unchanged rates. RBA Governor Michele Bullock stressed that further monetary tightening was necessary to prevent more serious economic difficulties, while Treasurer Jim Chalmers acknowledged that the decision would place additional pressure on Australian households. Following the announcement, AUDUSD declined, extending its losing streak to a third consecutive session as the Australian dollar weakened against its US counterpart.
In the bond market, longer-dated US Treasuries have outperformed, suggesting stronger demand for debt securities with longer maturities. This may reflect both expectations of easing inflationary pressures following yesterday's decline in oil prices and greater investor caution regarding the outlook for equities.
Signals from Iran remain mixed. Iranian President Masoud Pezeshkian suggested that the country's supreme leader had granted him greater flexibility to pursue peace negotiations. Meanwhile, according to Iranian broadcaster Press TV, the Islamic Revolutionary Guard Corps (IRGC) captured two US MQM-170 drones over Qeshm Island and destroyed what it described as the 55th American MQ-9 drone east of the Strait of Hormuz. These military claims have not been independently verified.
At the same time, Donald Trump expressed optimism about the possibility of reaching an agreement, linking the decline in oil prices to improving diplomatic prospects. The approaching US congressional elections are increasing the significance of geopolitical developments for financial markets. Trump's latest comments suggest that an immediate resumption of military strikes after the elections is not a foregone conclusion.
Apple (AAPL.US) reported revenue of $114.5 billion (+12% YoY) and net income of $30.71 billion for Q4 FY2026, exceeding analysts' expectations. The main growth drivers were iPhone (+17% YoY) and Mac (+24% YoY), while earnings per share (EPS) reached $2.10 versus the $1.99 consensus, partly supported by one-off tariff-related refunds. Despite the strong results, weaker-than-expected sales in China and declining revenue from iPads and wearables, Apple shares barely reacted to the report, trading near $338.50 in after-hours trading.
Palantir Technologies (PLTR.US) reported a 96% year-over-year revenue increase in Q3 2026 to $2.31 billion, beating the $2.18 billion consensus, although shares initially fell around 2.5%. US commercial revenue surged 149% year over year, while adjusted EPS reached $0.44 versus expectations of $0.41, with adjusted operating income of $1.43 billion. Management raised its full-year guidance, projecting 91% revenue growth in 2026, but the muted market reaction suggests that investors have already priced exceptionally strong growth into the stock's valuation.
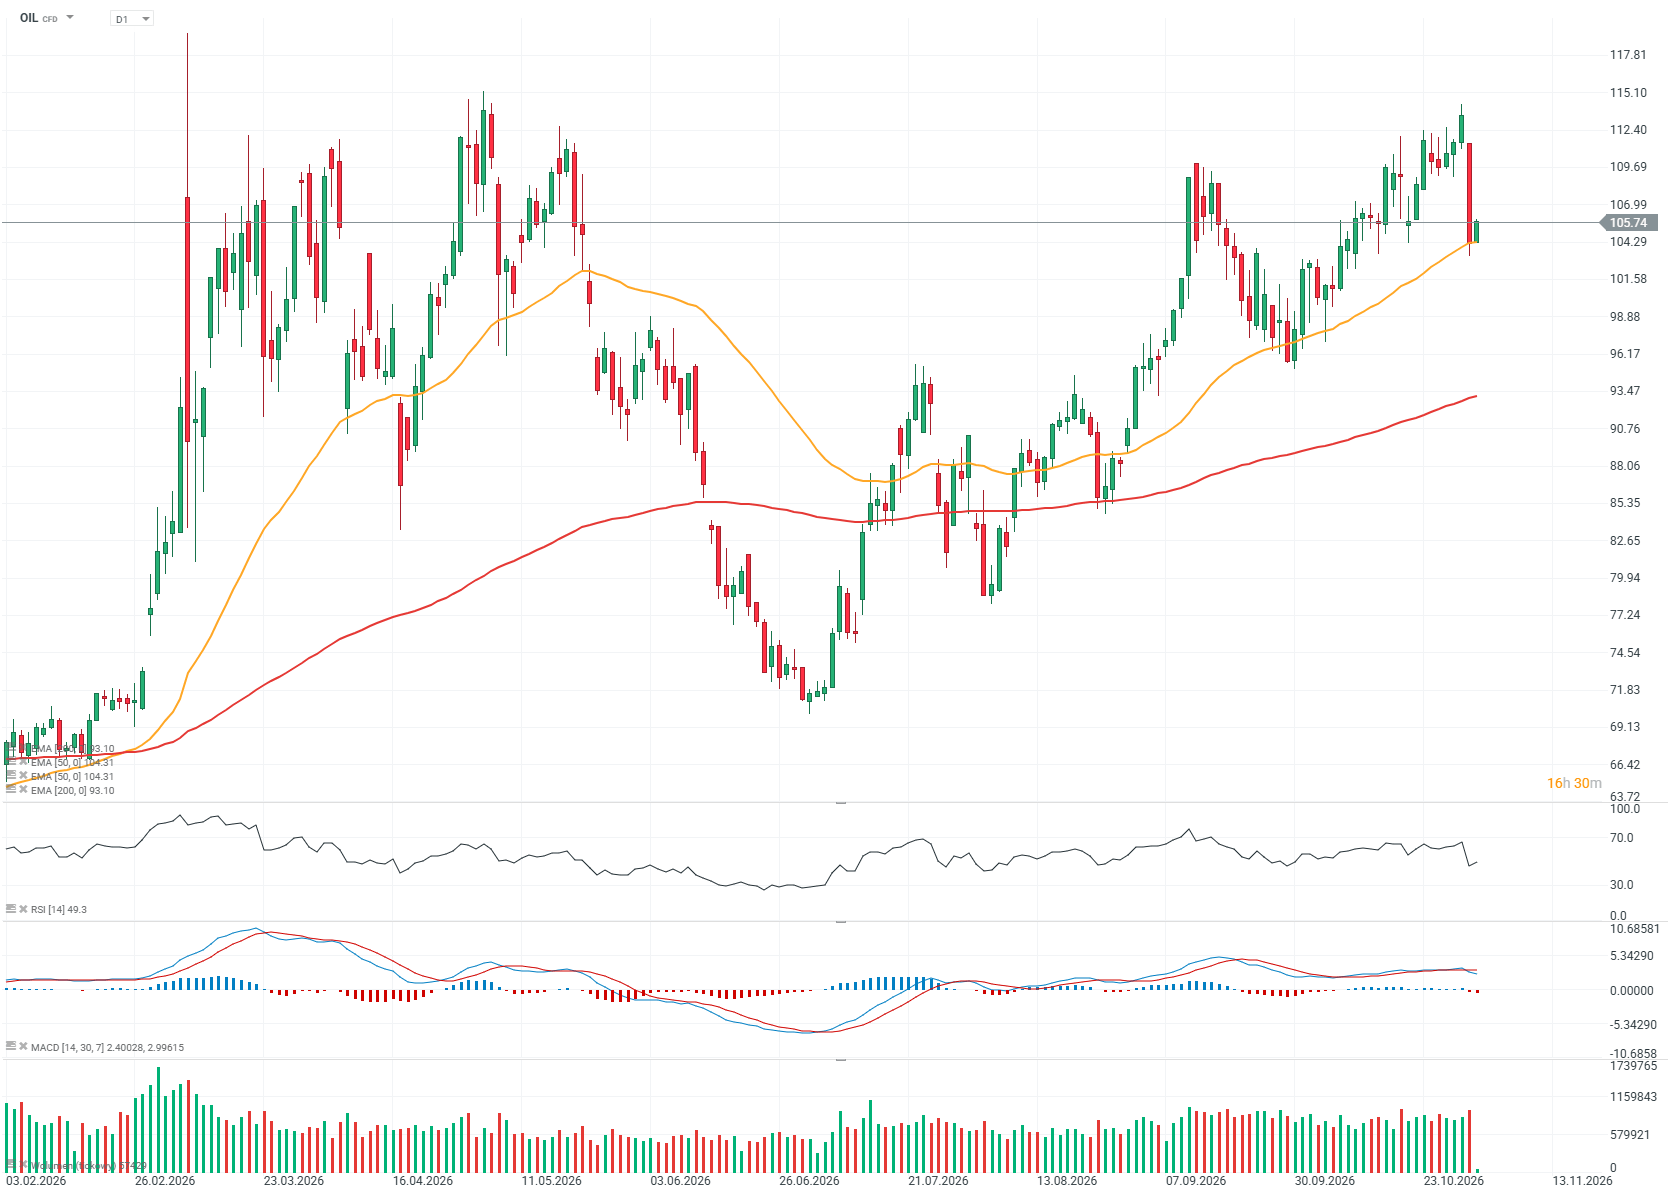
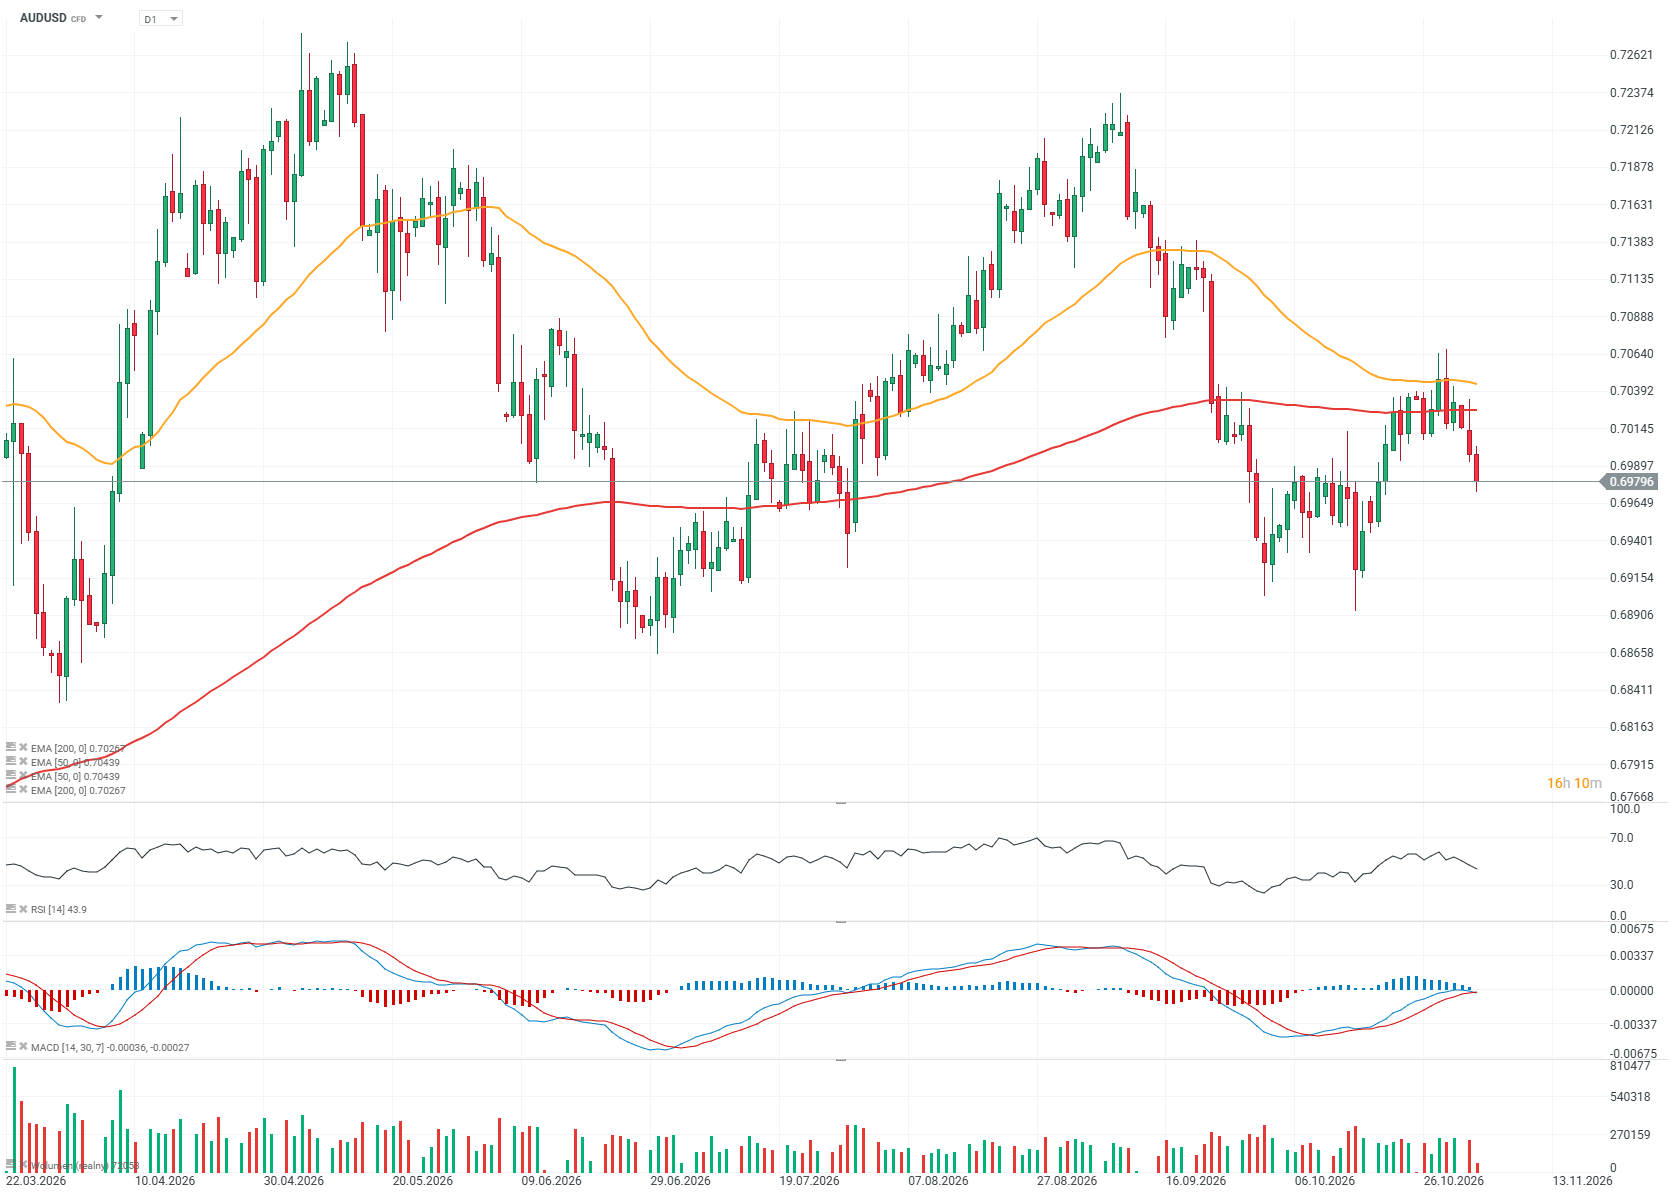
OIL, AUDUSD (D1 chart)
Brent crude futures have risen only modestly so far, but the reported US strike on Qeshm Island appears to highlight the substantial differences that remain between Washington and Tehran. It is difficult to imagine such an attack taking place if negotiations were progressing smoothly. Oil prices found support at the 50-period exponential moving average (EMA50, orange line), and the ongoing rebound could theoretically still push Brent above $110 per barrel.
Source: xStation5
AUDUSD is falling for the third consecutive session, slipping below its 200-period exponential moving average (EMA200, red line) and signalling a shift towards a bearish trend. The RSI stands at around 44, well above oversold territory, while a bearish MACD crossover could support the scenario of further declines. The 0.698 and 0.691 levels represent important support zones, while 0.703 remains a key resistance level, reinforced by previous price reactions and the EMA200.
 Source: xStation5

BREAKING: BoE raises interest rates by 25pbs to 4%⏰


Norges Bank keeps rates unchanged, but leaves the door open to rate hikes. Is this really the end of the NOK strengthening, though?

Economic Calendar: Investors Await the Bank of England's Decision 🏛️


What Drives the Market❓Top Morning News ⏰ (November 5, 2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.