


The U.S. Securities and Exchange Commission (SEC) has opened the door to broader trading in “tokenized equities.” In a sense, this breakthrough decision reinforces a sentiment that has been building for months around expectations of integrating digital assets with the traditional capital market.
The September 17 decision came after further work on the CLARITY Act was blocked in the Senate. An administrative path to reform allows market liberalization to continue, but leaves investors with greater uncertainty about how durable the new rules will be.
- The new mechanism provides five-year, conditional exemptions from some regulatory requirements for “tokenized equity trading platforms” and “liquidity providers.”
- The “tokens” are intended to grant rights equivalent to traditional securities, including access to dividends and voting. Crucially, however, issuers may object to having their shares admitted to such trading. The framework excludes synthetic instruments that only track a share price.
- The scale of implementation remains experimental. The SEC anticipates limits on the number of instruments and on volume, disclosure obligations, and various technological safeguards. The regulatory changes are justified mainly by the economic potential of tokenization. As supporters of tokenized asset systems argue, they can streamline settlement, reduce servicing costs, and broaden access to liquidity.
Ultimately, all of this is meant to strengthen the financial system and support productive investment. However, realizing this potential still depends on issuers and market participants.
Bitcoin regains momentum
BITCOIN (D1) Chart
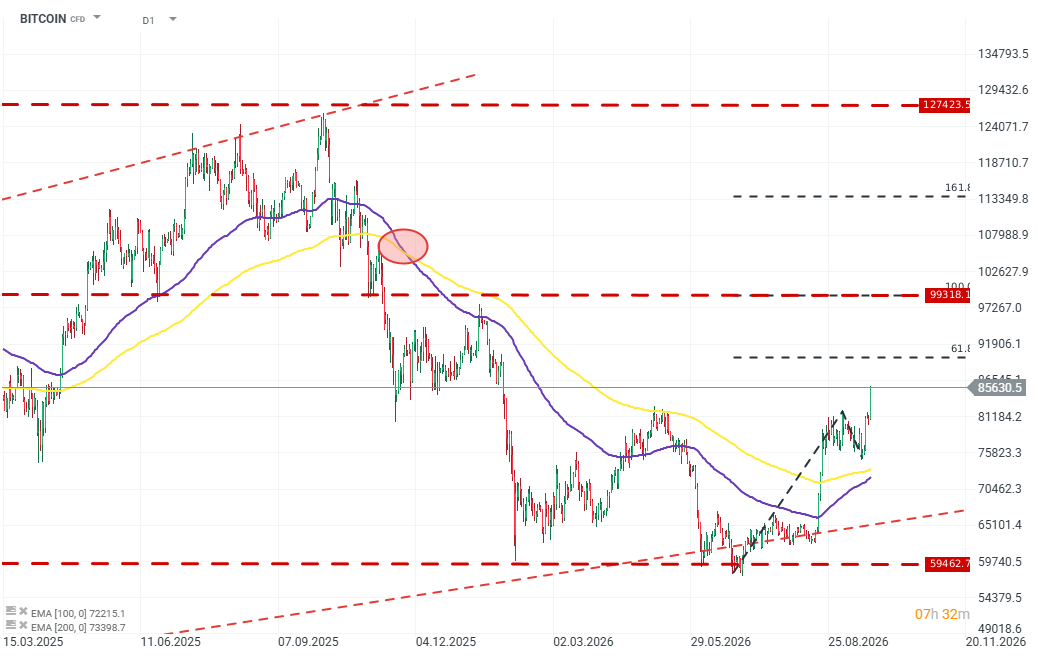
News of broader tokenization integration primarily supports cryptocurrencies and companies linked to their trading. On September 21, Bitcoin reached around USD 85,000, its highest level since January.
Among companies, Strategy shares rose 8%, while Coinbase and Robinhood gained 5%.
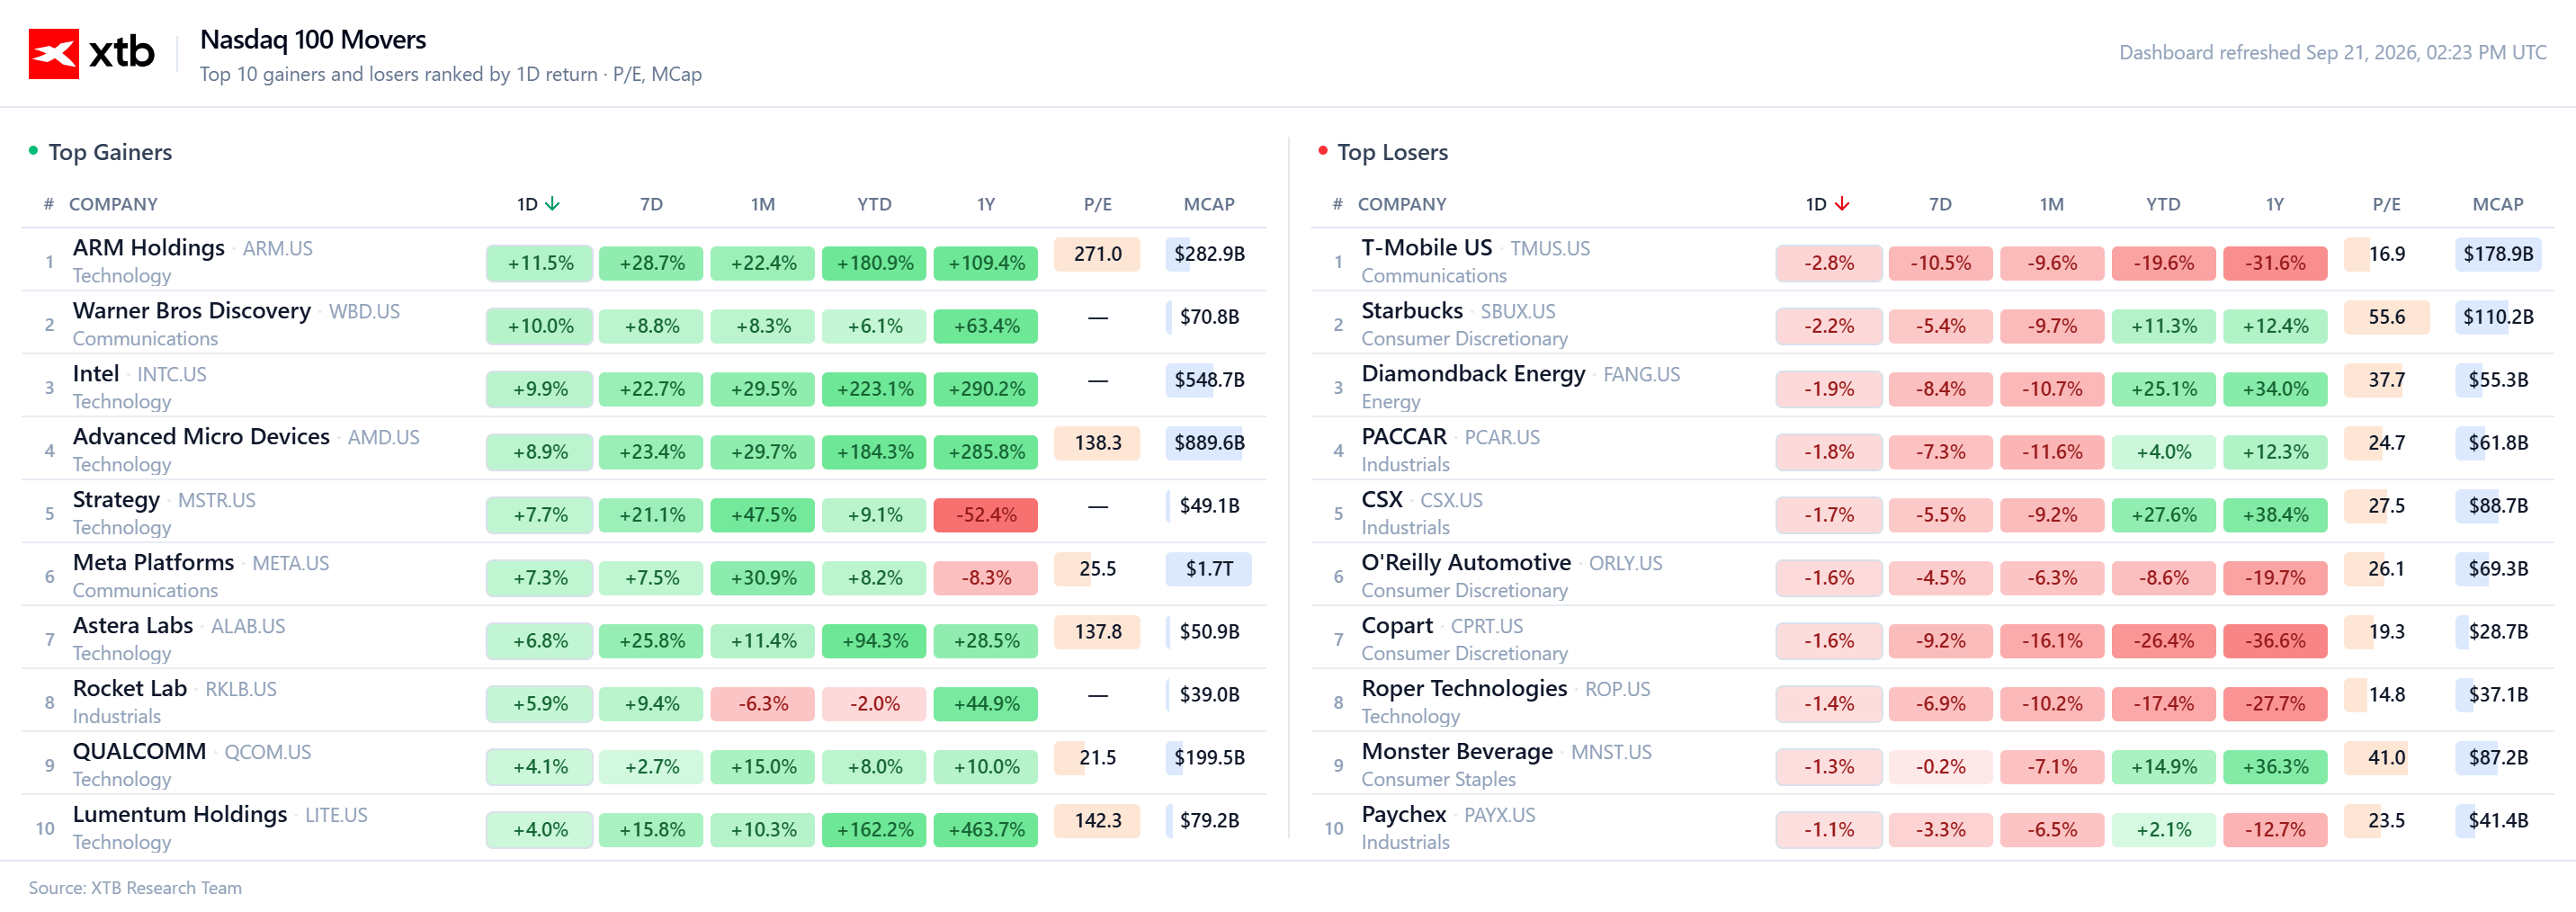
Attributing the entire move to the SEC decision would be an oversimplification. The market was also supported by inflows into Bitcoin ETFs and short covering. The regulatory boost also coincided with a moderate improvement in broader market sentiment, making it difficult to isolate the growth contribution for the assets mentioned in today’s session.
Importantly, tokenization’s relevance to Bitcoin is indirect. Wider blockchain use by financial institutions can increase acceptance of the whole asset class and willingness to allocate capital. Trading tokenized equities itself does not require a proportional increase in BTC purchases.
Strategy increases exposure to the rebound
Strategy benefits not only from Bitcoin price moves but also from a wave of fundamental news. The “treasury” type company reported buying another 950 bitcoin for USD 75.7 million, increasing its holdings to 846,000 BTC.
With a portfolio of that size, a USD 1,000 increase in the cryptocurrency price raises its gross value by about USD 846 million.
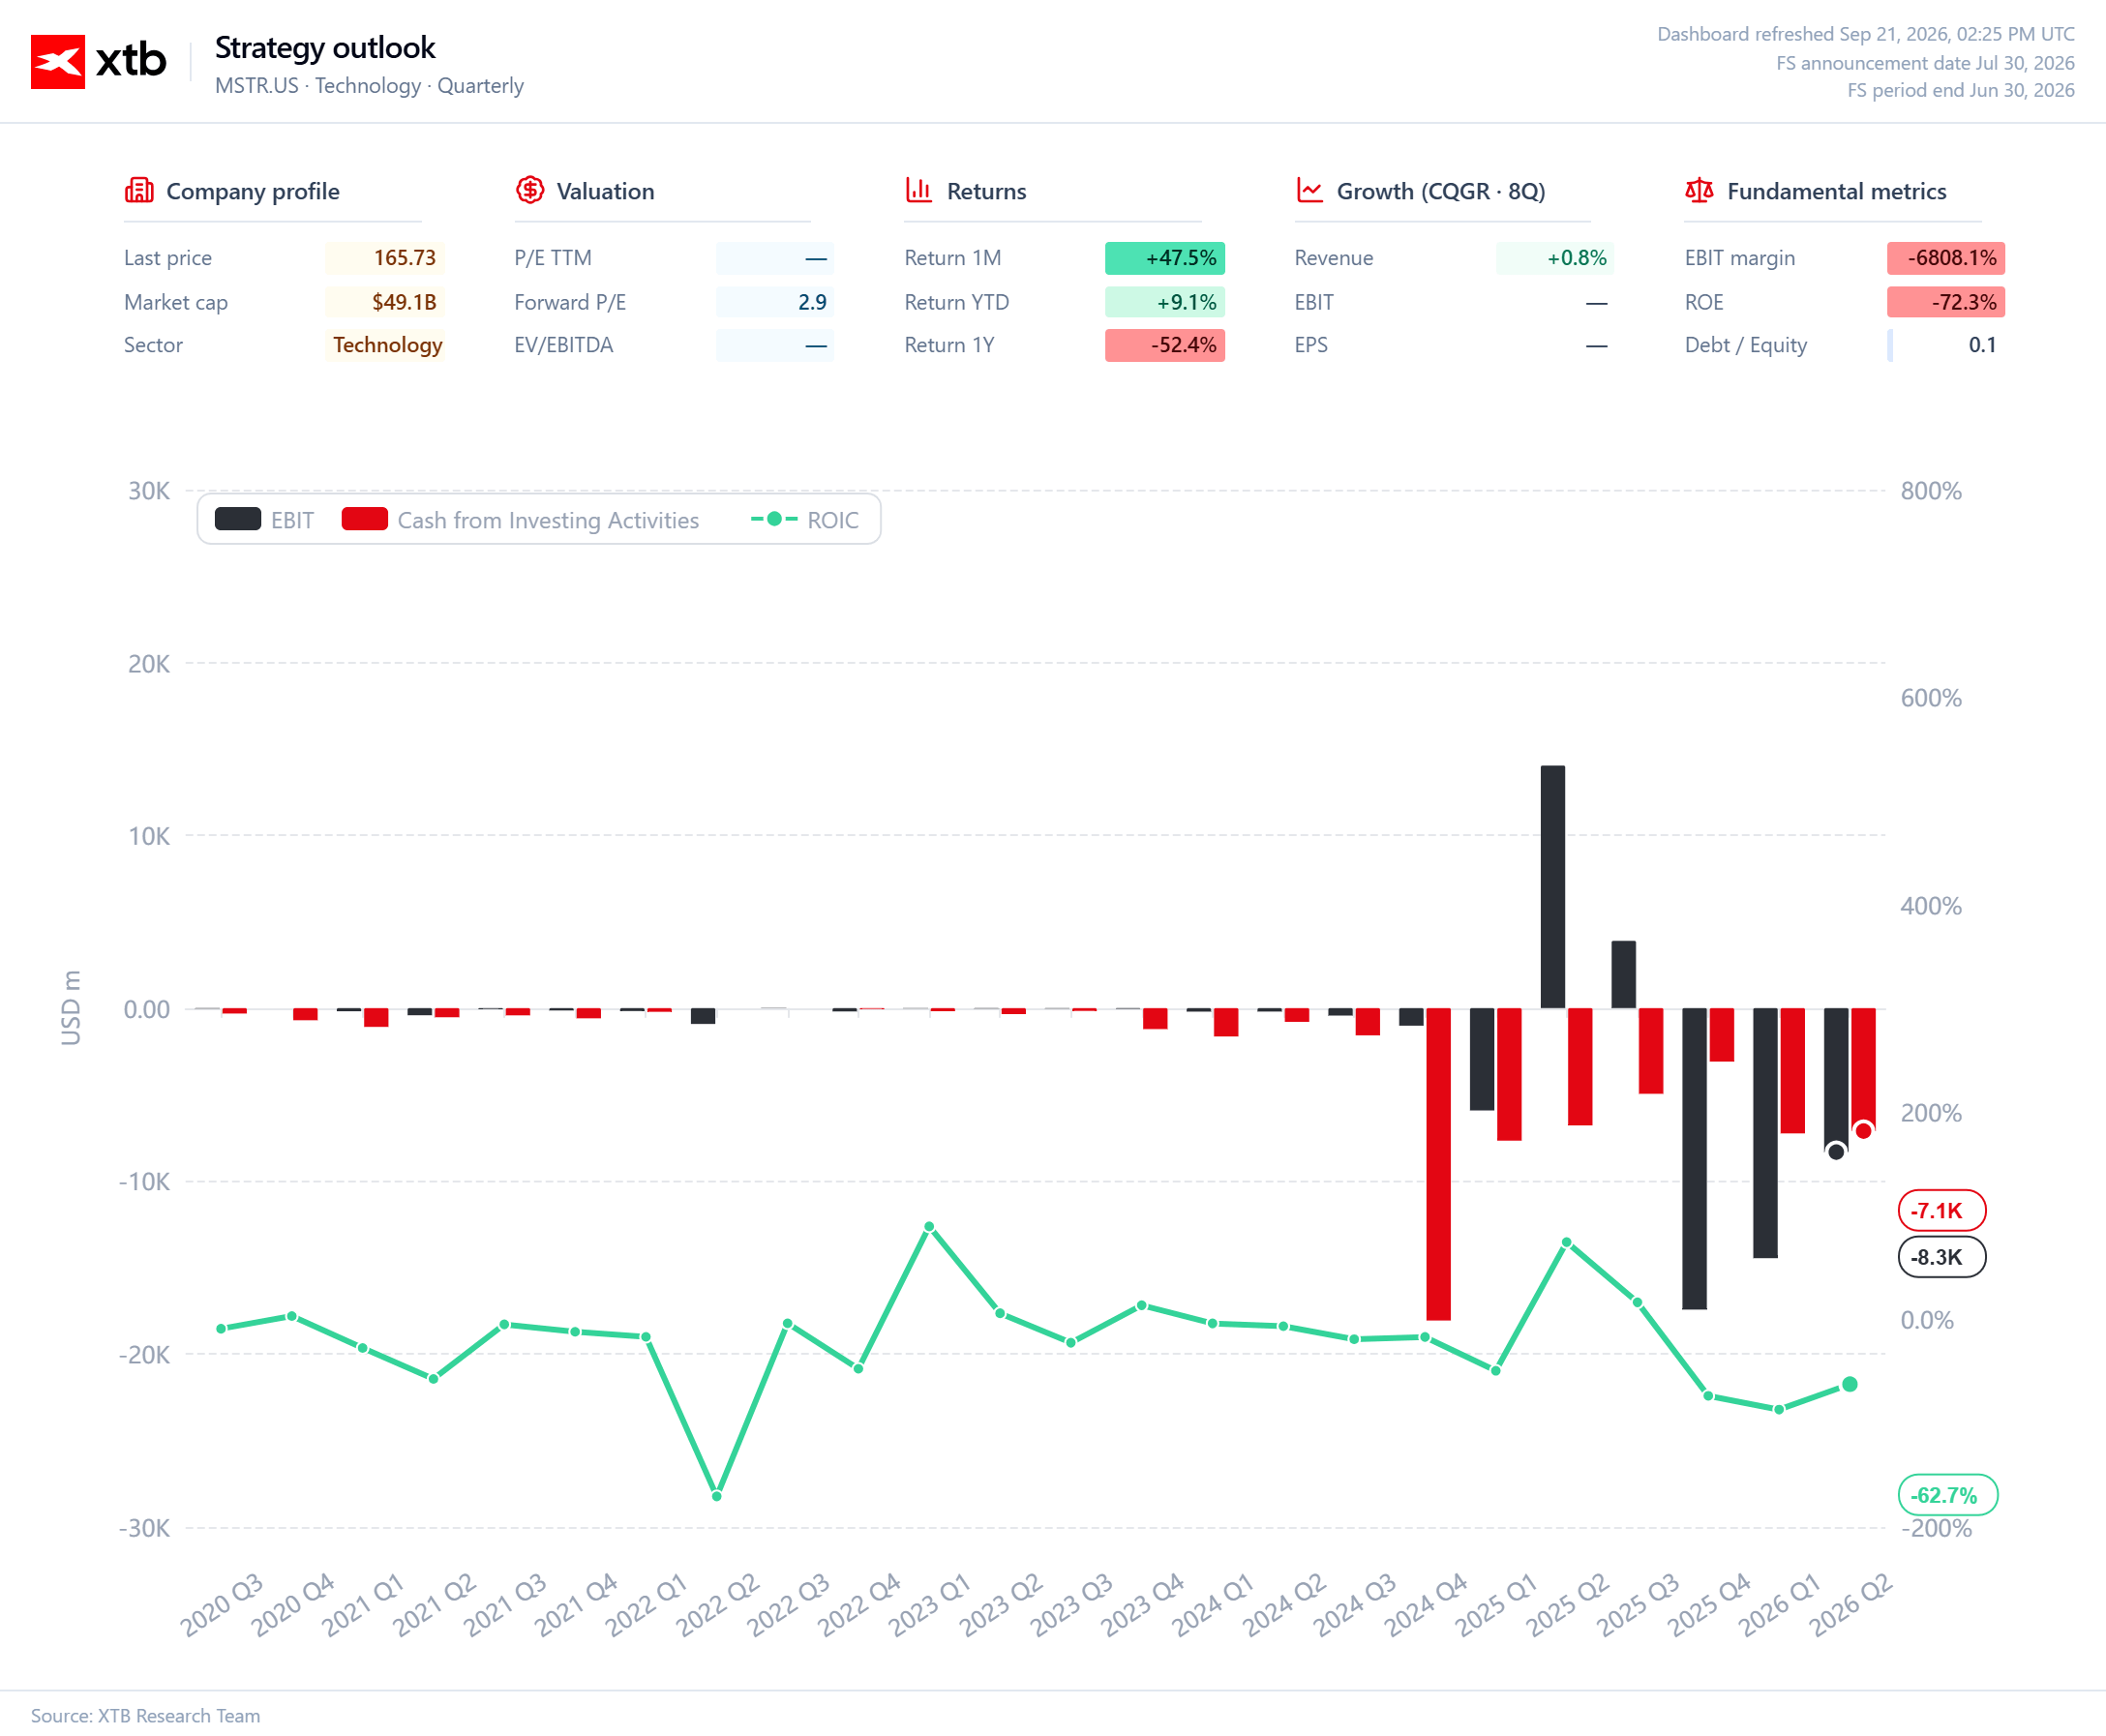
From a valuation perspective, the funding channel also matters. If a rise in Strategy’s share price increases its premium to net asset value attributable to common shareholders, share issuance can make further BTC accumulation easier. The benefit for existing investors depends on the issuance price, dilution, and the company’s obligations. A decline in that premium weakens the mechanism even if Bitcoin remains stable.

ARM Gains After CEO Comments, SoftBank Increases Financing


Daily Summary: Hawkish Fed fails to scare the markets (17.09.2026)

Nasdaq 100 Up 1.7%

US Open: Nasdaq, gold and silver surge following... an interest rate hike (17.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.